Lien Theory vs. Title Theory: What a Lien Theory State Means
When you take out a mortgage, who owns the house? You do. But how much the lender can claim before foreclosure depends on which theory your state follows. Here’s lien theory vs. title theory in plain English, plus why the state lists you find online don’t agree.
Lien Theory State: In a lien theory state, you keep legal title to your home when you take out a mortgage, and the lender holds only a lien as security. In a title theory state, the lender or a trustee holds title as security until the loan is paid off. In both, a lender has to foreclose to take the home for good.
Use this quick tool to see how your state is usually labeled:
Lien Theory vs. Title Theory, Side by Side
Most states follow lien theory. Cornell’s Legal Information Institute puts it this way: “Most states, however, follow the lien theory under which the legal title remains with the mortgagor.” The mortgagor is you, the borrower.

| Lien theory | Title theory |
|---|---|---|
Who holds legal title during the loan | You | The lender, or a trustee under a deed of trust |
What the lender holds | A lien as security | Title as security |
Lender’s right to possession before foreclosure | None, unless you agree, you abandon the property, or a court appoints a receiver | Yes in theory, unless the loan documents say otherwise |
How common | The majority of states | A minority of states |
Either way, you live there, pay the taxes, and build the equity. And either way, a lender who wants to take the home for good has to foreclose.
What Is an Intermediate Theory State?
A few states sit in the middle. Cornell describes intermediate theory as one that “applies the lien theory until there is a default on the mortgage.” Before default, it works like lien theory. After default, the lender gets title-theory rights, including the right to take possession.
Why It Matters to Owners and Landlords
Rents
This is the big one for rental owners. In a lien theory state, you keep possession and keep collecting rent until foreclosure. A lender that wants the rents first usually needs an assignment of rents in the loan documents and a court-appointed receiver. Under title theory, the lender has a stronger claim to possession, and with it the rents.
Joint tenancy
Say two people own a house as joint tenants and one of them mortgages their share. Under title theory, that mortgage severs the joint tenancy. Under lien theory, the majority view is that it doesn’t.
Paying it off
With a mortgage, the lender releases its lien when you pay it off. With a deed of trust, the trustee signs a deed of reconveyance to put full title back in your name.
Deeds of Trust Muddy the State Lists
A deed of trust adds a third party, the trustee, who holds title for the lender. That’s why many websites call every deed-of-trust state a “title theory” state. It’s not that simple.
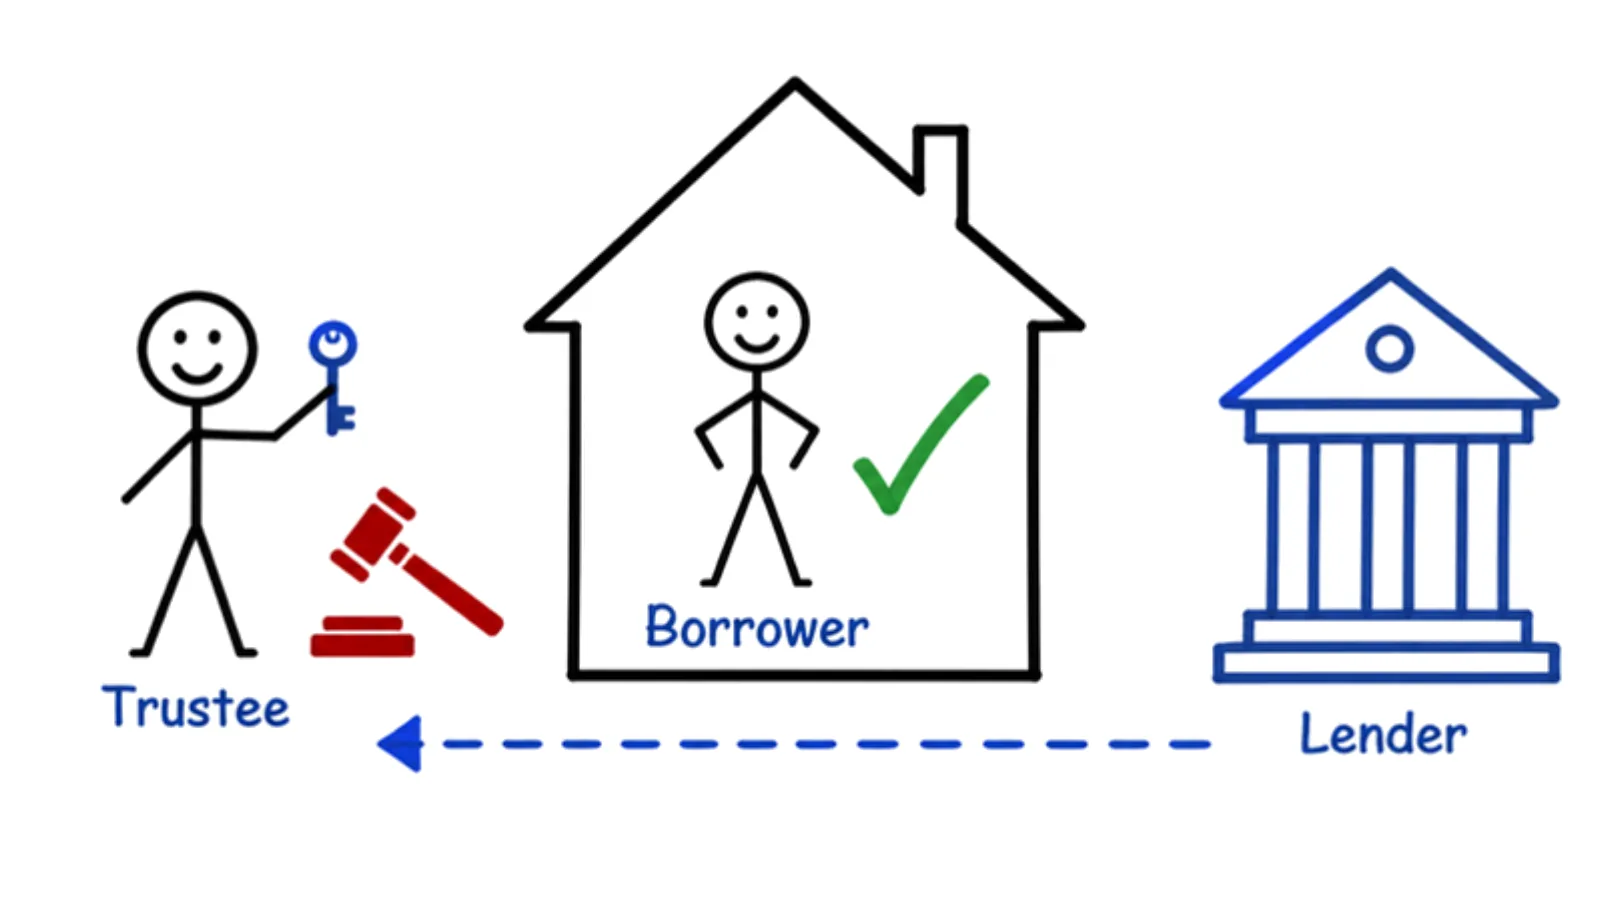
Courts have said a deed of trust works like a mortgage. The California Supreme Court put it this way back in 1933: while legal title passes, “it is practically and substantially only a mortgage with power of sale.”
Also, how a state forecloses is a separate question. Judicial foreclosure goes through court. Nonjudicial foreclosure uses the trustee’s power of sale. Plenty of pages mix up “title theory,” “deed of trust state,” and “nonjudicial foreclosure state.” They overlap, but they aren’t the same thing.
Which States Are Lien Theory States?
The lists don’t match. Sources agree that states like New York, Florida, Illinois, and New Jersey follow lien theory, and that Georgia follows title theory. After that, labels split, especially for deed-of-trust states and intermediate states like Ohio and Pennsylvania.
Use the tool above as a starting point. If the label matters for a real decision, like a foreclosure or a rent dispute, ask a local real estate attorney.
Here’s How It Looks in Idaho, Our Home State
Idaho is a good example of why the lists disagree. For mortgages, Idaho Code §6-104 is classic lien theory: “A mortgage of real property shall not be deemed a conveyance, whatever its terms, so as to enable the owner of the mortgage to recover possession of the real property without a foreclosure sale.”
Then Idaho passed its Trust Deeds Act in 1957. In Long v. Williams (1983), the Idaho Supreme Court said Idaho “transitioned from a ‘lien theory’ state to a ‘title passes’ state where a deed of trust is employed.” In the same opinion it called a deed of trust “for practical purposes only a mortgage with power of sale.”
Idaho’s statute keeps the trustee’s title narrow. Under Idaho Code §45-1502(4), the trustee holds title only for the power of sale and to reconvey, and “all other incidents of ownership of such real property shall remain with the grantor.” If a trustee’s sale does happen, notice has to go out at least 120 days before the sale (§45-1506(2)), and the borrower can reinstate within 115 days of the recorded notice of default (§45-1506(12)).
Lien Theory FAQs
What is the difference between a lien theory and a title theory state?
In a lien theory state, you hold legal title and the lender holds a lien. In a title theory state, the lender or a trustee holds title as security until the loan is paid off.
Who holds the title in a lien theory state?
You do. The lender’s interest is a lien recorded against the property.
Is a deed of trust state a title theory state?
Not necessarily. The trustee holds title, but only for limited purposes, and courts often treat a deed of trust like a mortgage with a power of sale. That’s a big reason state lists disagree.
Is Idaho a lien theory state?
For mortgages, yes (Idaho Code §6-104). For deeds of trust, the Idaho Supreme Court has called Idaho a “title passes” state, while still treating the deed of trust like a mortgage with a power of sale.
Does it change my monthly payment?
No. It changes the lender’s rights if you default, not your rate or payment.
Bottom Line
Lien theory vs. title theory decides who holds title on paper and what the lender can do before foreclosure. It doesn’t change who lives in the house or who builds the equity. See title theory states for the other side. Buying or investing in eastern Idaho? Bellhaven Real Estate can walk you through what you’re signing.