What Is an Operating Statement in Real Estate? (With an Example)
An operating statement is the scoreboard for a rental property. It shows what the property brought in, what it cost to run, and what was left over. If you’re buying a rental, refinancing one, or just trying to figure out if yours is making money, this is the report you want in front of you.
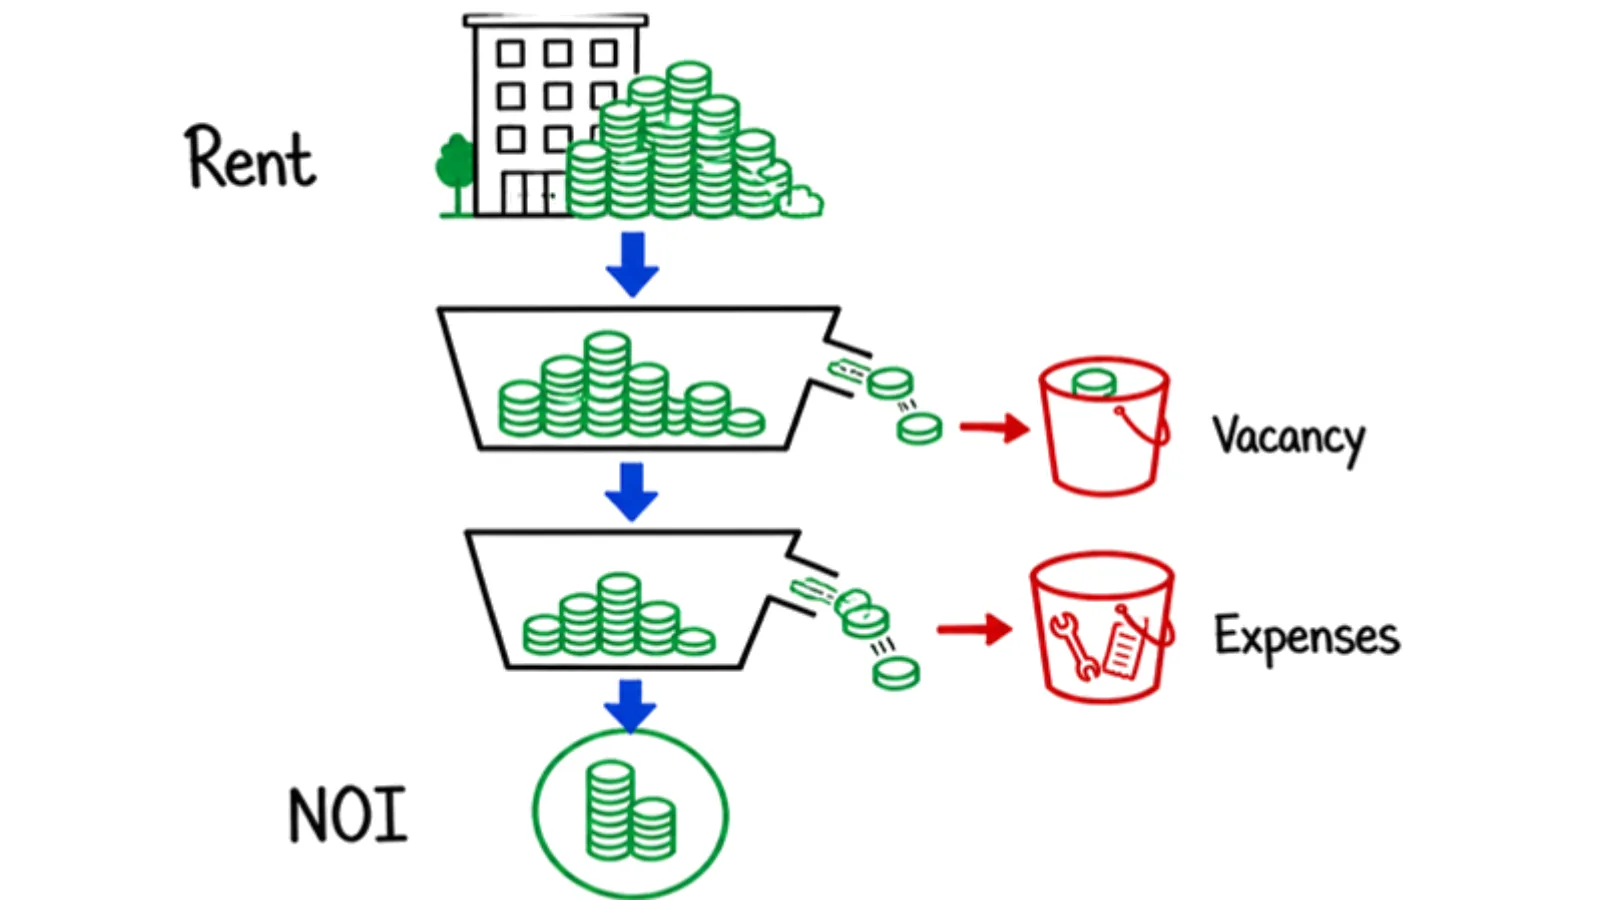
Operating Statement: A real estate operating statement is a report of a rental property’s income and operating expenses over a set period, usually a month, a year, or the trailing 12 months. It starts with gross potential rent, subtracts vacancy and credit loss to get effective gross income, then subtracts operating expenses to land on net operating income (NOI).
The lines on an operating statement
Every operating statement follows the same path from top to bottom. Learn these six lines and you can read any of them.
Gross potential rent (GPR). What the property would collect if every unit was rented all year at full rent.
Vacancy and credit loss. Rent you didn’t collect because a unit sat empty or a tenant didn’t pay. See vacancy rate.
Other income. Laundry, pet rent, late fees, storage, parking.
Effective gross income (EGI). GPR minus vacancy, plus other income. This is the money that actually came in. More on it in effective gross income.
Operating expenses. The cost of running the place: property taxes, insurance, repairs, utilities the owner pays, management, lawn and snow, advertising. Our operating expenses guide lists what counts.
Net operating income (NOI). EGI minus operating expenses. This is the number buyers and lenders care about most. See net operating income.
Operating statement example: a fourplex
Here’s a simple one for a made-up fourplex renting at $1,400 a unit per month. The numbers are for illustration only, but the math is real.
Line | Annual amount |
|---|---|
Gross potential rent (4 units x $1,400 x 12) | $67,200 |
Less vacancy and credit loss (5%) | -$3,360 |
Plus other income (laundry, pet rent, late fees) | $1,200 |
Effective gross income | $65,040 |
Property taxes | -$4,200 |
Insurance | -$2,800 |
Property management (8% of EGI) | -$5,203 |
Repairs and maintenance | -$4,000 |
Water, sewer, and trash | -$3,600 |
Lawn care and snow removal | -$1,500 |
Advertising and admin | -$600 |
Total operating expenses | -$21,903 |
Net operating income (NOI) | $43,137 |
The expense ratio here is about 33.7% ($21,903 divided by $65,040). That means roughly a third of every dollar collected goes to running the building.
What does NOT go on an operating statement
This is where most owner-made operating statements go wrong. These items sit below NOI, not inside it:
The mortgage payment. Principal and interest are debt service. They depend on how you financed the property, not how the property performs.
Capital improvements. A new roof or furnace isn’t a repair. The IRS treats it the same way. IRS Publication 527 says, “You must capitalize any expense you pay to improve your rental property.”
Depreciation and income taxes. Those belong on your tax return, not on the property’s scoreboard.
So in the example above, if the mortgage is $2,100 a month ($25,200 a year), cash flow before taxes is $43,137 minus $25,200, or $17,937. Same building, same NOI. A buyer with a different loan would have a different cash flow.

Heads up: your tax return is a different animal. Pub 527 notes that expenses like “maintenance, insurance, taxes, and interest” can generally be deducted from rental income on Schedule E. Mortgage interest belongs there. It just doesn’t belong in NOI.
Operating statement vs. income statement, pro forma, T12, and rent roll
People use these words loosely, so here’s the short version.
Document | What it shows | Actual or projected? |
|---|---|---|
Operating statement | Property income and operating expenses, down to NOI | Actual |
Income statement (P&L) | A whole business’s revenue and expenses, including interest, depreciation, and taxes, down to net income | Actual |
Pro forma | The same lines as an operating statement, but for what the property should do | Projected |
T12 (trailing 12) | An operating statement for the last 12 months, month by month | Actual |
Rent roll | Each unit, tenant, rent, and lease date on one day. No expenses. | Actual (a snapshot) |
An income statement and an operating statement are cousins. Cornell’s Wex dictionary even lists “statement of operations” as another name for the income statement. In real estate, though, “operating statement” almost always means the property-level report that stops at NOI. If you want the unit-by-unit side, see rent roll.
How buyers and lenders use it
NOI drives most of the math in a rental deal:
Cap rate. NOI divided by price. Our fourplex at a $575,000 price is a 7.5% cap rate ($43,137 / $575,000). More in capitalization rate.
Debt service coverage ratio (DSCR). NOI divided by the yearly mortgage payments. With $25,200 in debt service, the fourplex covers its loan about 1.71 times. See DSCR.
Expense ratio. Operating expenses divided by EGI. Way too low is usually a red flag, not a win.
For a 1-4 unit home loan, lenders often look at rent a little differently. Fannie Mae’s Selling Guide (B3-3.8-02) has the lender “multiply monthly gross rent by 75%” when it counts rental income from the property you’re buying. The other 25% is a cushion for vacancy and upkeep.
Red flags when you read a seller’s operating statement
A seller’s operating statement is a sales document. Read it like one. Here’s what to check first:
No management fee. The owner manages it themselves. You still need to budget for it, even if you plan to self-manage, because your time isn’t free.
Zero vacancy. Every rental has turnover eventually. A statement that never shows a vacant month is either very lucky or incomplete.
Tiny repair line. Deferred maintenance shows up as a big bill later, usually right after you buy.
Old property taxes. Taxes can change after a sale or reassessment. Use what you’ll pay, not what the seller paid.
Pro forma dressed up as actuals. Ask for the T12 and the rent roll, then make sure they match.
Do this now: Pull last year’s numbers on your own rental and line them up in the order above. If you don’t know your NOI to the dollar, you don’t really know what the property is worth.
A simple operating statement template
Copy this into a spreadsheet, one column per month, with a total column at the end:
Gross potential rent
Less vacancy and credit loss
Plus other income
= Effective gross income
Property taxes
Insurance
Property management
Repairs and maintenance
Utilities paid by owner
Lawn, snow, and cleaning
Advertising and admin
HOA dues (if any)
= Total operating expenses
= Net operating income
Keep capital items like a roof or water heater on a separate list. Our CapEx calculator helps you plan for them so they don’t wreck a year.
FAQs
What is an operating statement?
A report of a property’s income and operating expenses over a period, ending at net operating income (NOI).
Is an operating statement the same as an income statement?
Close, but not quite. A business income statement keeps going past operating profit to include interest, depreciation, and taxes. A property operating statement stops at NOI.
Does the mortgage go on an operating statement?
No. The mortgage is debt service and sits below NOI. That’s why two owners of the same building can have the same NOI and very different cash flow.
What is a T12 operating statement?
The last 12 months of actual income and expenses, usually broken out by month. Buyers and lenders ask for it because it shows real results, not projections.
What are examples of operating expenses?
Property taxes, insurance, repairs and maintenance, owner-paid utilities, management fees, lawn and snow, and advertising. Not the mortgage, and not capital improvements.