What Is a Yield Spread Premium (YSP)?
If you’re reading old closing papers, or a loan officer just said “YSP,” here’s the short version. The yield spread premium is mostly history. The trade behind it is still alive, though, and today it shows up on your Loan Estimate as a lender credit.
Yield Spread Premium (YSP): A yield spread premium (YSP) was money a lender paid a mortgage broker for delivering a loan at an interest rate above the lender’s base, or par, rate. The higher the rate, the bigger the payment. Since April 6, 2011, federal rules have banned paying loan originators based on the interest rate, so the old YSP is gone.

How a Yield Spread Premium Worked
Every lender has a par rate for a loan. That’s the rate where the lender pays no extra and charges no points. HUD’s 1999 RESPA policy statement described yield spread premiums as payments “based on the interest rate and points … as compared to the par rate offered by the lender to the mortgage broker.”
Here’s a hypothetical. Par on a $300,000, 30-year loan is 6.50%. The mortgage broker delivers the borrower at 6.75% instead. The lender likes that higher rate, so it pays the broker 1% of the loan, $3,000. That $3,000 is the yield spread premium.
Sometimes the broker used that money to cover the borrower’s closing costs. Sometimes the broker kept it on top of the origination fee the borrower already paid. That second one is where the trouble started.
Why Yield Spread Premiums Were Banned
A YSP paid brokers more for putting people in higher rates. In 2010 the Federal Reserve said lenders “commonly pay loan originators more compensation if the borrower accepts an interest rate higher” than the rate the borrower qualifies for. Its new rule shut that down. Starting April 6, 2011, loan originators can’t be paid based on the interest rate or other loan terms.
Dodd-Frank Section 1403 put the same idea into federal law at 15 U.S.C. §1639b, and the CFPB’s updated rule took effect January 10, 2014. Today it lives in Regulation Z, 12 CFR §1026.36(d):
No pay based on loan terms. A loan originator’s pay can’t be based on the rate or other terms of the loan (§1026.36(d)(1)).
No double dipping. If you pay the broker directly, the broker can’t also get paid by the lender on that loan (§1026.36(d)(2)).
Brokers still get paid by lenders. That part’s legal. It just can’t swing up or down with the rate you take, and it can’t stack on top of a fee you paid the broker yourself.
What Replaced YSP: Lender Credits
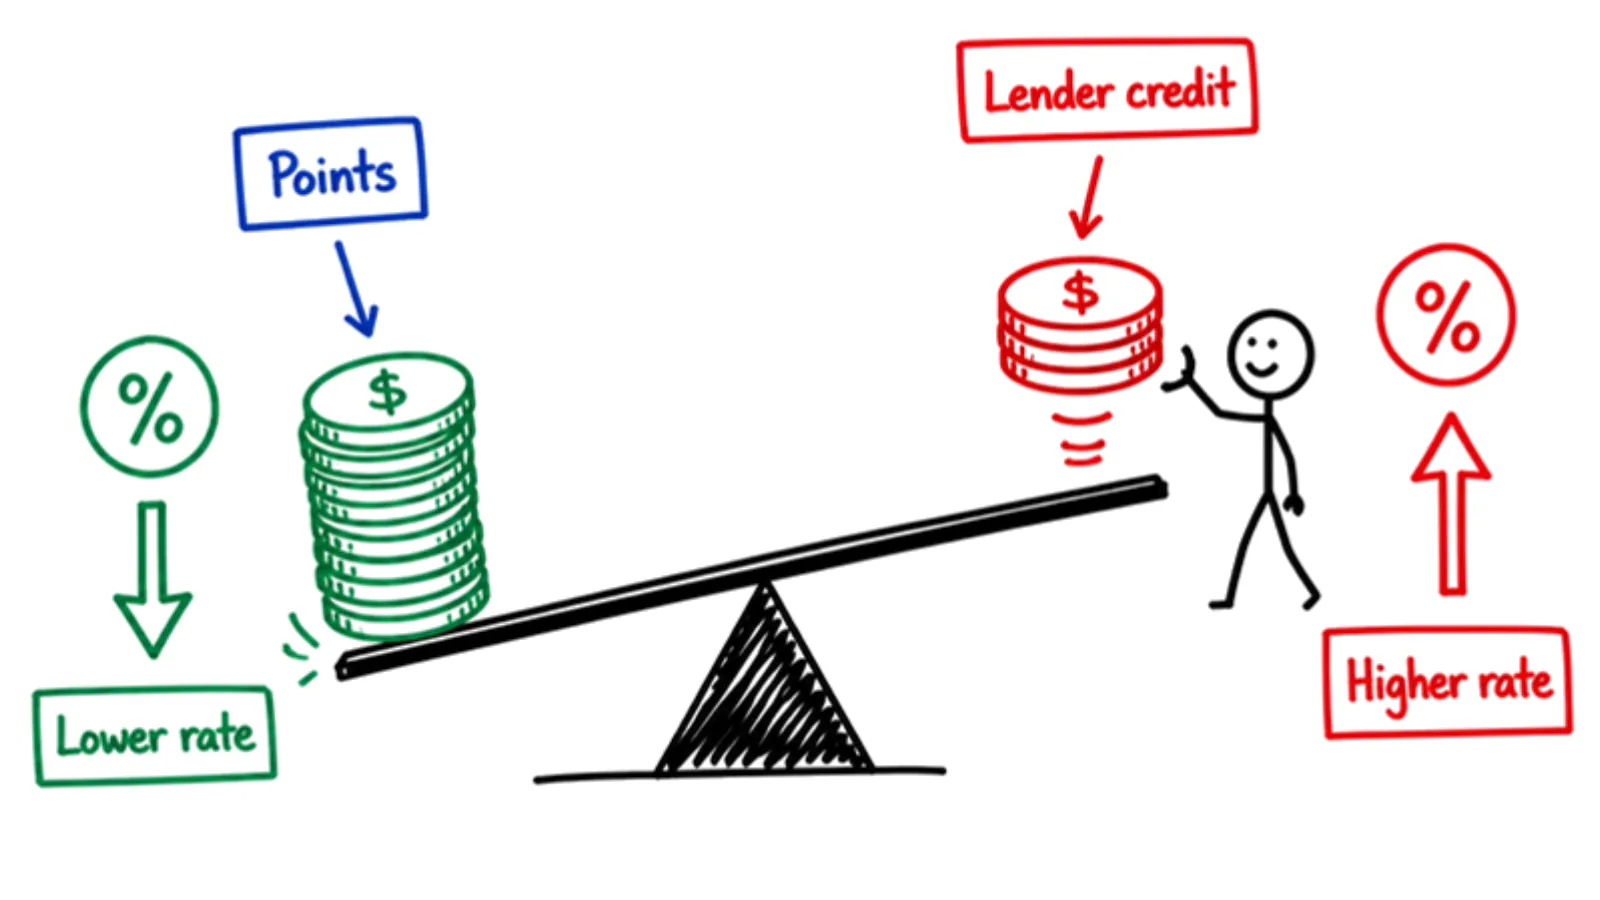
You can still trade a higher rate for lower closing costs. It’s called a lender credit now, and the money goes toward your costs, not into the loan officer’s paycheck. The CFPB puts it plainly: “Lender credits lower your closing costs up front, in exchange for a higher interest rate.”
The flip side is discount points. You pay more at closing to get a lower rate. One point is 1% of the loan, so $3,000 on a $300,000 loan. Lenders sometimes call a lender credit “negative points.”
| Discount points | Lender credit |
|---|---|---|
Cash at closing | More | Less |
Interest rate | Lower | Higher |
Where it shows on the Loan Estimate | Page 2, Section A | Page 2, Section J (as a negative number) |
Usually makes sense if you | Plan to keep the loan a long time | Expect to sell or refinance in a few years, or you’re short on cash to close |
Do the Math Before You Take a Lender Credit
Same hypothetical loan. At 6.50% the principal and interest payment is $1,896.20 a month. At 6.75% it’s $1,945.79. That’s $49.59 more every month in exchange for a $3,000 credit.
Get three quotes from the same lender: one at par, one with points, one with a lender credit.
Find the payment difference. Here, $49.59 a month.
Divide the credit by that difference. $3,000 ÷ $49.59 = about 60 months.
Compare it to your plans. Keep the loan longer than about five years and the credit ends up costing you more than it saved.
DO THIS NOW: Pull up your Loan Estimate and look at page 2, Section J. If there’s a negative number on the Lender Credits line, ask your lender what rate you’d get without it.
Where You’ll See It on Your Paperwork
On a loan you’re getting now, look at the Loan Estimate and the Closing Disclosure. Lender credits sit in Section J on page 2. Points and origination charges sit in Section A. If the lender pays the broker, that compensation isn’t itemized on the Loan Estimate, but it does show up on the Closing Disclosure.
On an older loan, the 2010 Good Faith Estimate showed it as a credit “for the specific interest rate chosen,” and the HUD-1 settlement statement showed the lender’s payment to the broker on line 802.
Here’s an Idaho example. Idaho Code §26-31-211(3) says mortgage brokers and lenders can’t “accept any fees at closing that were not previously disclosed fully to the borrower.” Every state handles broker licensing a little differently, but the federal compensation rules above apply everywhere.
Yield Spread Premium FAQs
Are yield spread premiums legal?
Not the old way. Since April 6, 2011, a loan originator can’t be paid more for steering you into a higher rate. Lenders can still pay brokers a fee that doesn’t depend on the rate.
Is a lender credit the same as a YSP?
Close, but no. Both come from a higher rate. A YSP could end up in the broker’s pocket. A lender credit has to go toward your closing costs.
How was YSP calculated?
It was based on how far the borrower’s rate was above the lender’s par rate. Higher rate, bigger payment. The exact amount came from the lender’s rate sheet that day.
Do mortgage brokers still get paid by lenders?
Yes. Lender-paid compensation is allowed as long as it isn’t tied to your rate or loan terms, and the broker isn’t also collecting a fee from you on the same loan.
Bottom Line
The yield spread premium is gone, but the rate-for-cash trade isn’t. Ask for quotes at par, with points, and with a credit, then run the break-even. Buying in eastern Idaho? Bellhaven Real Estate can help you compare offers before you lock.